Introduction
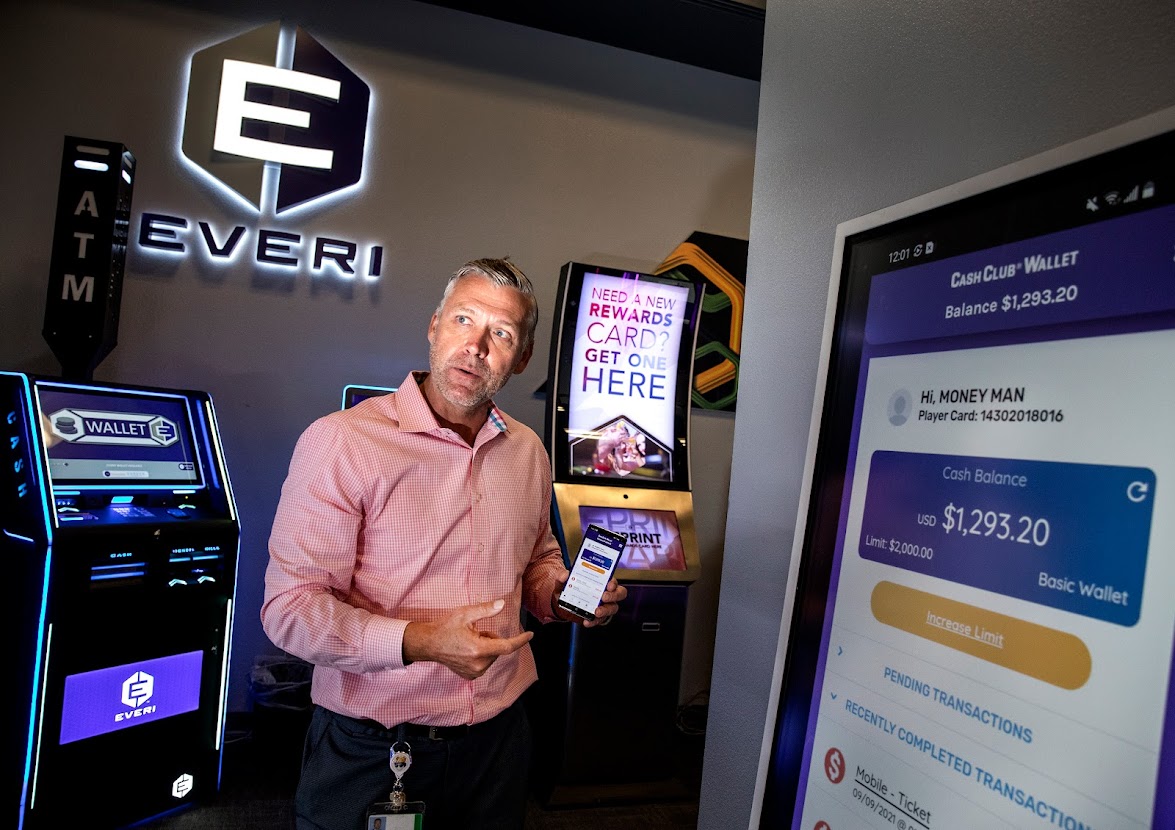
Digital banking has changed how people manage money. Customers can check balances, transfer funds, review statements, and authorize transactions through online banking portals or mobile applications rather than relying entirely on in-person services.
These developments have also influenced payment processing for online casino platforms. Where permitted by law and supported by the relevant financial institutions, digital banking services can provide a direct route between a customer’s bank account and a merchant’s payment system.
The technology offers convenience, but it also depends on banking infrastructure, authentication requirements, fraud controls, and the policies of participating institutions.
Online Banking and Electronic Transfers
Online banking allows customers to initiate financial transactions through a bank’s digital interface. Depending on the country, available services may include domestic bank transfers, instant payment networks, and other electronic transfer options.
When a merchant supports a bank payment, the customer may be redirected to a banking service or asked to approve a transfer through an authorized interface.
The bank then processes the request according to its own procedures and the rules of the relevant payment network. The merchant receives transaction information through its payment provider and updates the account when the appropriate status is confirmed.
This arrangement can reduce the need to manually enter card information. However, the process varies across banks and countries, and not all gambling-related payments are supported.
Real-Time Payment Services
Some countries have developed payment networks designed to move money between participating accounts within seconds or close to real time.
These services can improve the speed of eligible transfers and provide clearer confirmation of payment status. They may also support transfers outside traditional banking hours, depending on the network.
However, real-time transfer capability does not mean every payment is guaranteed to complete instantly. Banks may apply security checks, transaction limits, account restrictions, or additional verification.
Availability also depends on whether the merchant’s payment provider is connected to the relevant network and whether the transaction type is permitted.
Customers should check the bank’s terms and the merchant’s payment information before assuming that a particular transfer will be immediate.
Open Banking and Account Connectivity
In some jurisdictions, open banking frameworks allow customers to authorize regulated third-party providers to access specified financial information or initiate certain payment services.
These arrangements use secure interfaces and permission-based access rather than requiring customers to share their online banking passwords directly with a merchant.
Depending on local rules, an authorized service may help verify account details, initiate a payment, or provide confirmation that a transfer has been requested.
Open banking does not provide unrestricted access to a person’s finances. Access is limited by the customer’s authorization, the provider’s permissions, and applicable legal requirements.
Customers should review what information a service requests, why it needs that information, and how consent can be withdrawn.
Authentication and Fraud Controls
Digital banking relies on security systems designed to protect account access and payment authorization.
These may include passwords, one-time codes, banking applications, biometric checks, transaction notifications, and device recognition. Banks can also apply risk-based verification when an activity appears unusual.
Such controls help reduce the risk of unauthorized transfers, but they cannot prevent every form of fraud. Phishing messages and fake banking pages may trick customers into revealing credentials or approving a payment they did not intend to make.
Customers should access banking services through official applications or verified websites. They should never disclose passwords or verification codes to people claiming to represent a bank or merchant.
If an unfamiliar payment appears, contacting the bank promptly through an official channel is important.
Transaction Records and Payment Confirmation
Digital banking systems create electronic records that help customers and financial institutions track transfers.
Depending on the payment network, these records may include a transaction reference, date, amount, recipient information, and status. Such details can help support teams investigate delays or discrepancies.
However, a transfer receipt may indicate only that a payment instruction was submitted or accepted. It does not always establish that the merchant has received and matched the funds.
Payment status can pass through several stages, and the bank’s display may not update at the same time as the merchant’s account. Customers should keep transaction references and follow the provider’s guidance if a transfer remains unresolved.
Compliance and Financial Monitoring
Digital banking services operate within legal and regulatory frameworks that vary by country. Financial institutions may be required to verify customers, monitor transactions, maintain records, and investigate certain types of activity.
Online gambling payments can be subject to additional restrictions depending on local law and bank policy. Some institutions may block or decline transactions connected with gambling businesses.
A merchant may also need to complete identity checks and monitor payment activity under the rules applicable to its license.
These procedures can create extra steps, but they are part of the broader system for managing financial risk and complying with legal obligations.
Benefits and Limitations
Digital banking can provide familiar account-based payments, electronic records, and convenient access through mobile applications. In markets with modern transfer networks, it may also support faster movement of funds.
At the same time, users need to consider bank fees, transfer limits, processing windows, supported payment types, and withdrawal arrangements. An outgoing payment may be handled differently from a refund or merchant withdrawal.
Customers should compare the complete payment process rather than focusing only on the speed of the initial transfer.
Conclusion
Digital banking technology plays an important role in connecting customers, financial institutions, and online merchants. Electronic transfers, real-time payment networks, authorized account connections, and secure authentication help support modern payment experiences.
Yet the availability and timing of casino-related payments depend on local regulations, bank policies, and merchant integrations. Understanding those conditions, protecting banking credentials, and keeping transaction records can help customers manage digital payments more carefully.
Frequently Asked Questions
What is digital banking in casino payments?
It refers to the use of online banking services and electronic transfer systems to initiate or manage eligible payments involving an online casino.
Are digital bank transfers always instant?
No. Processing depends on the payment network, participating institutions, verification requirements, and transaction type.
What is open banking?
Open banking allows authorized providers to access specified financial information or initiate supported services under permission-based rules and applicable regulations.
Why might a bank block a gambling transaction?
The bank may apply legal restrictions, merchant-category rules, fraud controls, or its own account policies.
What information should customers keep after a transfer?
They should retain the transaction reference, date, amount, payment status, and relevant correspondence until the transfer is fully resolved.
One Reply to “The Role of Digital Banking Technology in Casino Payments”